How to Send Money to Brazil: Transfers, Costs, and Property Payments
Sending money to Brazil is more complex than most foreign citizens expect. Brazil has a history of extensive regulation of money entering and leaving the country. Banks in Brazil must check where the money comes from and why it is being sent. Sending the wire is only the first step: the recipient must be able to use the funds. This guide covers everyday transfers as well as the extra planning needed for a property purchase.
Reviewed by Luciano Oliveira, Esq., LL.M. · October 2026
Brazil’s foreign exchange rules were overhauled by the new Foreign Exchange and International Capital Law (Lei 14.286/2021), in force since the end of 2022, and the Central Bank regulations issued under it. The new framework simplified procedures and modernized nonresident accounts. In practice, however, do not expect a revolution when moving large amounts: banks still review the people, documents, and purpose behind the payment.
Legal basis: Law 14,286/2021, articles 3–4 — the authorized institution must identify its clients and check that the exchange is lawful. The customer states the payment purpose, with guidance from the institution.
You can also read this page in Portuguese. Don’t forget to check our FAQ section located at the end of this page.
Before you read: cross-border money transfers have serious legal and tax implications when done wrong. This guide is general information, not legal advice, and not an endorsement of any provider mentioned. Before moving significant funds, seek advice from a lawyer licensed in Brazil and check any requirements in the country you are sending from.
1. Allow time for the money to become available
Brazilian banks may take several days or even weeks to release large amounts — there is no single amount that triggers a delay — requiring that the receiving party provide many documents and get registered with their currency exchange departments.
Why can a transfer take longer than expected?
Currency exchange departments in traditional Brazilian banks can take a long time to review the documents and approve the transaction. There can also be a substantial disconnection between the bank back-office and the branch personnel. Language barriers may bring more friction to the mix. Ask who will handle the review and how the recipient can contact them.
Why should I care? Isn’t sending a wire transfer my only obligation as a buyer?
Unfortunately not. Although it may take only a few minutes to send a wire transfer from the USA, the UK, or Europe, the transfer will not help you meet a payment deadline unless the recipient actually gets the money! It is not uncommon for Brazilian banks to return wire transfers to the country of origin after the recipient party fails to satisfy the bank’s requirements.
So, if I get the paperwork right, is the release of my wire transfer guaranteed?
No. It is never guaranteed. For the most straightforward and well-supported transactions, the recipient bank may still ask further questions before releasing the funds. The problem is that transactions involving large sums are not always interpreted as “straightforward” by the banks. Do not agree to a payment date based only on the sender’s delivery estimate.
Are you sending this money to buy property, make an investment, or move a large sum? If so, “which app is cheapest” is not the only question. Confirm that the provider accepts the amount, purpose, sender, and recipient before sending it. Some apps support property payments, but that does not mean every purchase is suitable for that route. See paying for a property in Brazil for help coordinating payment with closing.
Three Ways to Transfer Money to Brazil
Learn the three main ways to send money to Brazil, their pros, and their cons.
- 1) Small Amounts – Web Platforms. If you are transferring small payments to family, friends, or even a small downpayment upon signing a property purchase contract, you may want to compare apps such as Wise and other money-transfer services. US$10,000 is a useful reference point when comparing these services, but it is not a universal limit. Confirm the available amount and payment purpose before relying on an app for a downpayment.
- 2) Higher Amounts – Everyday Banks in Brazil. If you need to send an amount higher than US$10,000, compare the app’s actual limit with a bank transfer. Traditional banks may work as long as you are willing to endure the document checks and possible delays involved. Make sure you have solid documentation to support your transfer and have your lawyer agree on when the seller is paid. Sending through a bank does not remove the risk of paying before you obtain ownership.
- 3) Large Amounts – Attorney along with a Currency Exchange Bank. Currency Exchange Banks in Brazil (not the same as currency exchange houses or exchange bureaus) may represent a better alternative for a transaction needing more coordination. Currency Exchange Banks work well when paired with an attorney or law firm experienced in cross-border transactions.
2. Transferring Smaller Amounts to Brazil — Money Apps
Brazil’s rules allow digital international payment services, including services known as eFX. Different providers use different arrangements. The important question is whether the service can handle your particular transfer under the applicable rules.
Keep US$10,000 in mind when comparing money apps. It is a threshold you will encounter in some services and payment categories. For example, Wise currently lists US$10,000 for transfers to Brazilian business accounts, while some transfers to personal accounts can be higher. Other apps have their own limits. Treat US$10,000 as a practical reference point, not a rule that all apps stop there or that smaller payments avoid document checks.
Legal basis: BCB Resolution 277/2022, as amended — sets the rules for foreign exchange and international payment services, including eFX. Provider limits must also be checked; US$10,000 is not a general ceiling on all international transfers.
Wise
We are aware of a large number of foreign individuals successfully sending money to Brazil through Wise.
Caps are substantially higher than they used to be for some transfers. Check the current limit for your sender and recipient types in Wise’s BRL transfer guide and in your quote. Wise lists property purchase among its payment purposes, but acceptance still depends on the particular transfer. Confirm documents, costs, and timing before committing to a payment deadline.
Warning: the fact that you have transferred funds to Brazil successfully through Wise in the past does not mean you will continue to be able to do so. Many of our clients have reported increased document requirements over time (e.g., copies of passport, source of funds, etc.) and refusal of additional transfers.
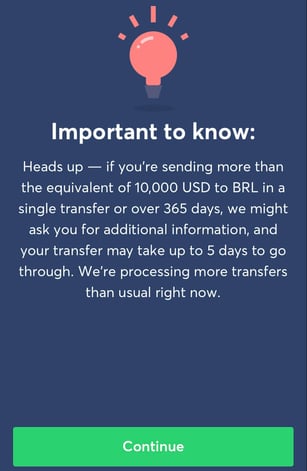
Copy of an actual warning from Wise.
Being aware of such risks is important so you don’t end up learning you cannot send more money right before a payment deadline is up.
Remitly
Remitly is an option to compare in the US–Brazil corridor. Check whether the recipient’s Pix or bank account is supported. Part of the cost may be in the exchange-rate markup rather than an explicit fee, and sending limits depend on your account and country. To unlock higher limits you may need to submit more identity and source-of-funds documentation. First-transfer promotions may not apply to later payments.
Xoom
Xoom is PayPal’s dedicated international remittance product. Check its Brazil service separately from regular PayPal. Compare speed, the available funding methods, and payout options. The exchange-rate markup and any card-funded transfer fees matter as well as the advertised fee. Confirm the options for your country and amount before sending.
As for regular PayPal: We do not recommend using Paypal for remitting money to a party in Brazil. We have personally experienced issues related to Paypal withholding funds. The last thing you want to happen when sending money to honor a contract is Paypal sitting on your money while you face the risk of severe contractual penalties being triggered.
Western Union
Western Union offers international transfers to Brazil. Depending on the available service, the recipient may receive the money in an account or collect cash. While you can send money to Brazil by depositing in a Western Union store in your country of residency for the Brazilian counterparty to withdraw the funds in Brazil, limits vary by location and service. Check before relying on this route.
Revolut
If you already hold a Revolut account, check whether its current Brazil transfer options fit your payment. Compare the exchange rate, plan charges, supported recipient, and delivery estimate. Features available in one country or plan may not be available in another.
Comparison tools and other processors
Monito has an interesting business model. It is a comparison site, not a transfer service: it asks you some basic info about your remittance and then shows how the actual processors would handle the transaction along with associated fees. Among Monito’s partner processors are Wise, MoneyGram, and others.
Depending on where you are sending the funds from, you may want to check other money remittance processors such as MoneyGram, WorldRemit, Skrill, Paysend, and Remitly.
Important: we do not endorse any of these services here described. It is up to you to select and investigate the trustworthiness of the money remittance processor. Check the provider and the payment instructions before sending.
3. Receiving money through a Brazilian bank
In this section, we discuss the use of traditional banks in Brazil when transferring money from abroad.
How to Pick Banks in Brazil
Traditional banks in Brazil, such as Bradesco, Itau, and Banco do Brasil, usually take several days to process a wire transfer from abroad. It is not uncommon for people to wait weeks until the funds are released.
Banks specializing in currency exchange may be faster for some transfers. They can review documents and advise on what is missing before you send. Ask whether they expect to get a wire transfer released in just a few days or need more time; there is no guaranteed timeline.
Check the receiving branch’s experience
When a party tries to receive a wire transfer in smaller Brazilian towns or branches in the suburbs, local experience may vary. A branch with little experience with international wire transfers may need help from a specialist team. Ask to speak to the team responsible for currency exchange rather than relying only on a branch estimate.
Explain these situations to the bank before sending:
- you want yourself or another person to receive the funds on your behalf to pay the seller at closing;
- your source of income comes from a business instead of employment;
- a parent or a relative will be paying part or all of the cost (see also our note on gift tax below).
For a property purchase, agree on who receives the money and when
- Send the money directly to the seller
Sending the payment directly by bank transfer (e.g.: from your Chase, Bank of America, Barclays, Revolut, etc.) to the seller may be the preferred approach for sending a smaller downpayment agreed in the contract. The amount alone does not make the payment safe. Have your lawyer check the seller, property, and payment terms first.
Risk of paying before closing. We don’t like to see our clients paying large amounts to the seller by bank transfer before closing.
Sending a full payment to sellers before the closing will put you at risk since a seller may not necessarily attend the closing later on (e.g., seller dies between payment and closing date, seller changes his mind about selling, or seller intends to defraud the buyer).
The seller handles the receiving bank. The biggest upside of sending money directly to a real estate seller is that this person is highly motivated to be paid.
As long as you give the seller a clear warning about the fact that their bank will ask them for lots of documents and require a lot of communication, the seller will be the one bearing the burden of making the bank release the funds. But a receiving-bank delay can still leave you facing the contract’s payment deadline.
- A representative may arrange payment at closing
Through a power of attorney (POA), you can have a lawyer or a family member representing you at the closing. A POA does not by itself mean a bank will accept money into the representative’s account. Your lawyer must check the authority, account arrangements, and safeguards before any funds are sent.
The POA holder may, if the bank and seller agree, use your funds to obtain a certified check at the bank and use this certified check to pay the seller during the closing. The advantage of this approach is that the seller will not get your money until the moment that they sign the deed. Signing the deed is not the final transfer of ownership. The purchase must also be registered at the property registry. Agree on payment and registration safeguards with your lawyer.
Legal basis: Brazilian Civil Code, article 1,245 — for a property sale, ownership passes through registration of the transfer at the property registry.
Can you trust the person holding the money? Sending your money to someone in Brazil involves substantial risk. Is this person reliable? Who controls the account, and what happens if the transaction does not close? A POA is not an escrow arrangement.
If you hold a suitable Brazilian bank account, you may be able to pay from your own account at closing. Your lawyer should agree on the payment method with the bank and seller in advance. A bank-issued check, TED, or Pix may be considered, depending on the arrangements. Check payment limits and cut-off times before signing day.
4. Specialist currency-exchange providers
Using currency exchange-specializing banks is our standard recommendation for clients purchasing real estate in Brazil. Read more to know why. The right provider still depends on the transaction; an app or everyday bank may suit some payments.
You need a legitimate reason to send large amounts of money to someone in Brazil. The legitimacy of such transactions is closely evaluated by Brazilian banks before release. The two main factors involved in such analysis are: (a) Where the funds came from and (b) Purpose of the transfer.
Most of our clients need to send a large amount of money when buying real estate properties in Brazil. For this purpose, banks will focus their analysis on: (a) evidence showing where the purchase money came from and (b) documents supporting the property purchase. The money may come from savings, a property sale, inheritance, or a loan—not only current income.
It is common for our clients to say, “the red tape involved in getting a transfer of money to Brazil is unbearable.” Many of our clients decide to hire us after missing the closing date, incurring substantial penalties under their contracts, and being threatened to be sued by the seller.
How are they different from everyday banks?
Everyday banks in Brazil are banks such as Bradesco, Itau, and Banco do Brasil. Most of them have branches. Banks such as Nubank and Banco Inter do not have branches, but they are also focused on traditional banking operations. Such banks have currency exchange departments in their back-offices that may not be closely integrated with their branches or customer service channels.
There can be disconnection and friction when you use such banks. They may limit their money transfer services to transactions that fit neatly in what they see as straightforward transactions. An international money transfer that goes beyond the basic may need extra review. Ask whether a dedicated team will handle the transfer and answer questions about the documents.
Currency exchange banks in Brazil will usually stay away from traditional banking operations and focus their resources on currency exchange and a few other specialized types of transaction. They may offer competitive exchange rates and transfer fees, but compare the full quote rather than assuming they will be cheaper.
Examples to investigate, not a ranking
- Ouribank
- Moneycorp Banco de Câmbio
- Braza Bank
- BTG Pactual
- Banco Rendimento
Offerings and onboarding policies change, so confirm directly. We have no commercial affiliation with any of them, and this is not an endorsement. Confirm the institution’s current status, whether it accepts your type of client, and whether it handles the proposed payment.
Here is the practical catch: some providers are not willing to work directly with consumers or have minimum transaction sizes. Ask who will handle your case, what their role is, and what they charge. For large transactions, an attorney can help organize the transaction the way the FX bank’s compliance desk expects it and time the exchange contract with the closing. The bank still makes its own decision about accepting the transfer.
When might a specialist be worth considering?
Reasons to compare a specialist with your everyday bank include: 1) Seller is unwilling or incapable of handling the legwork required to release funds through their own bank; 2) Your source of income is unconventional and everyday banks needs more explanation; 3) your tax returns alone do not explain the funds available for the purchase. A specialist must still check the source of the money; it is not a way around those checks.
Can I deal directly with the provider?
Even when working with a currency exchange bank, you would still have to decide to work with this bank directly or hire an attorney to help coordinate the transaction. The bank checks the transfer; your lawyer also checks the purchase contract and payment risks.
Large remittances to Brazil are highly scrutinized and the documents required depend on the transaction and the provider. Verify the status of any institution or intermediary you use. If someone takes your money and does not credit you in Brazil, recovering it may be difficult.
Experienced recipients. Professional sellers of luxury real estate in Brazil may be better prepared to interact with their bankers and enable such remittances to be received through a regular commercial bank such as Itau, Bradesco, Banco do Brasil, or Santander.
Recipients who have not handled this before. Some private sellers of real estate in Brazil have little experience with the red tape involved in receiving substantial sums of money from abroad. Such sellers may get into a sale transaction with a foreign buyer without understanding the complexity of such transaction.
Sellers may get annoyed when they do not get their money on time, buyers may get worried when their money gets entangled between the sender and the receiver bank, and attorneys may need to get involved when it is unclear if penalty clauses addressing late payment will be applicable or not. Agree in the contract how bank delays will be handled.
5. Holding reais in a nonresident account
There is a fourth route that deserves its own section: opening a Brazilian bank account as a nonresident. The CNR (Conta de Não Residente) — formerly known as the CDE (Conta de Domiciliado no Exterior), and a descendant of the old “CC5” accounts — is a regular account in reais held by someone who lives outside Brazil.
It is available both to foreign citizens and to Brazilians who live abroad (including those who filed the final departure tax declaration).
The new Foreign Exchange Law improved this arrangement. Under Lei 14.286/2021 and BCB Resolution 277/2022, Brazilian institutions can offer accounts in reais for nonresidents, subject to the applicable rules and their own account-opening checks. Not every bank offers one to individuals. Ask which account is available, what documents it needs, and whether it supports your planned transfers. A domestic payment from the account is not automatically a new currency exchange.
Legal basis: Law 14,286/2021, article 5, VIII and §4 — provides for nonresident accounts in reais, subject to Central Bank requirements. This does not require every bank to offer an account to every applicant.
How a CNR may help with a property purchase: you may be able to wire your own funds from abroad into your own CNR ahead of time, complete the bank’s checks before payment is due, and then pay the seller in reais at the closing — by TED or Pix, timed to the signature. You keep the leverage that is lost when the seller is paid weeks before closing, without needing to trust a POA holder with your money.
For clients who plan to keep ties to Brazil (maintenance costs, condo fees, utilities, future renovations), the account keeps working after the closing too. The account is not escrow: payment timing and registration risks still need to be managed.
The caveats: (1) Banks are selective with nonresidents, ask for proof of source of funds, and some institutions do not offer the product to individuals. Ask whether documents need authentication or translation. (2) The transfer into your own CNR is a same-owner transfer, but that does not automatically mean a higher IOF rate than paying the seller directly. Compare account charges and the full transfer quote. (3) You will need a CPF, and the account does not replace any tax declarations required for your situation. As always: structure first, then move the money.
6. Compare the total cost: exchange rate, IOF, and fees
IOF — the tax on the exchange. IOF (Imposto sobre Operações Financeiras) is the federal tax charged on the currency-exchange leg of your transfer, on the Brazilian side. The rates changed several times in 2025 and were litigated all the way to the Supreme Federal Court, so confirm the applicable rate on the day of your transaction. How a transfer is structured and its declared purpose can change its tax cost, which is one more reason to plan the route before signing a purchase contract.
Do not apply a rate for money leaving Brazil to money coming into Brazil simply because both accounts have the same owner. Ask the provider to identify the applicable IOF in your quote.
Legal basis: Decree 6,306/2007, article 15-B, as amended — sets IOF rates for different foreign-exchange transactions. The relevant category, including whether funds enter or leave Brazil, matters.
The spread — the markup in the exchange rate. The wire fee is only part of the cost. The spread is the difference between the mid-market rate (the one on Google) and the rate applied to your conversion. A “$15 fee” transfer with a 3% spread costs far more than a “$50 fee” transfer at a 0.5% spread on any meaningful amount.
When comparing quotes, use the same sending amount and check the final BRL amount after all taxes and fees. Ask about deductions by intermediary or receiving banks. Compare quotes at roughly the same time, since exchange rates move.
Legal basis: BCB Resolution 277/2022, article 18 — the total effective cost (VET) combines the exchange rate, applicable taxes, and charged fees. This supports comparing the full cost rather than the advertised fee alone.
7. Before committing to a property payment
What can you do to reduce the friction of such transactions? Plan the transfer before agreeing to a payment deadline:
- Allow time in the contract for the downpayment and closing payment. We recommend at least 60 to 90 days for closing after the contract signature. This is a planning recommendation, not a legal requirement or a promise that the bank will finish within that period. Agree on the dates for your transaction.
- Direct sellers to discuss with their bank account manager all the required documents and steps to receive the money sent from abroad. This helps ensure the seller is aware of the timeline and also get the documents required prepared early.
- Pay attention to how a purchase and sale agreement allocates the penalty in case of payment delays. Ideally, the buyer would have some extra time detailed in the contract to cover cases of delays caused by the complexities involved in the money transfer.
- Consider working with a Brazilian bank specializing in currency exchange, and ask how it handles large money remittances to Brazil.
- Factor in how friendly and willing to work through potential hiccups the seller is. A seller easy to work with may offset part of the red tape and challenges of remitting large amounts of money to Brazil.
- Avoid schemes designed to avoid the Brazilian regulations. Relying on non-registered financial providers and individuals engaged in dollar-cabo may result in a complete loss of your money in addition to civil penalties and criminal prosecution.
- Hire an attorney specializing in cross-border real estate transactions to assist you with your purchase.
8. Pix, money leaving Brazil, and family funding
Pix changed the last mile. Pix — Brazil’s instant payment system — can deliver the Brazilian part of a transfer quickly, around the clock. One common misconception, though: Pix is a domestic system. A foreign bank account does not send an international wire over Pix. What the apps do is convert your dollars, pounds, or euros and pay out the reais via Pix at the Brazilian end. To send Pix yourself, you need an account with Pix access at a participating Brazilian institution. You may use that account while abroad; ask your provider about eligibility and limits.
Sending money FROM Brazil. This guide covers money coming into Brazil. The reverse trip — repatriating sale proceeds, sending inheritance funds abroad, or moving your money out when you leave — has its own rules, taxes, and documentation. See our guide on transferring inherited funds from Brazil, or contact us about repatriation.
Family gifts and the gift tax (ITCMD). If a parent or relative is funding part of your purchase be aware that donations from abroad may also trigger Brazilian state gift tax (ITCMD). The constitutional rules changed with the 2023 tax reform and the states are updating their laws, so the answer is state-specific and time-specific. Decide whether the contribution is a gift, loan, or money from a co-buyer before the money moves — see our page on donations for the purchase of real estate. A family contribution is not automatically a gift. Its documents should reflect the real arrangement.
9. Practical questions about sending money to Brazil
How long does a wire transfer to Brazil take?
App transfers paid via Pix may arrive within minutes after approval. Traditional bank wires: the international leg may take several business days, but the release in Brazil is the real variable—from same-day release to several weeks for large amounts or missing documents. Plan 60–90 days between contract and closing for property purchases when appropriate to the transaction. This is a planning recommendation, not a promised bank-processing time.
Can I use Pix from the United States or Europe?
Pix is a domestic Brazilian system tied to accounts at Brazilian institutions. Foreign apps deliver your transfer into the recipient’s Pix after conversion and any required checks, but to send Pix yourself you need a Brazilian account. Having access to a Brazilian account while abroad is different from sending an international transfer over Pix.
Limits, cash, and accounts
Can I take money with me to Brazil?
Travelers to Brazil can bring up to US$10,000 (or equivalent) in cash without a Brazilian cash declaration. For amounts over that threshold, it is necessary that the person completes an e-DBV notice before arriving in Brazil and presents it to Brazilian Customs. Check the rules in the country you leave as well. You may still be asked to explain the origin and purpose of such money. In addition to the above inconvenience, there is also the risk of the cash being stolen. Therefore, we highly recommend that travelers to Brazil not carry significant amounts of cash on them. This threshold is not a limit on bank transfers.
Legal basis: Law 14,286/2021, article 14 — sets the cash-carrying framework. Receita Federal’s traveler guidance explains the e-DBV declaration procedure for cash above US$10,000 or its equivalent.
How much money can I send to Brazil?
There is no pre-fixed limit on how much money you can send to Brazil. Banks will review remittances on a case by case basis. Main factors considered are evidence of where your money came from and how well you can prove to the bank that the underlying transaction is legitimate. Providers may set their own limits for particular services or accounts.
Legal basis: Law 14,286/2021, article 2 — foreign-exchange transactions have no general statutory value ceiling, but remain subject to applicable rules. A provider may still impose service limits or refuse a transaction.
Is there a limit on how much I can send through apps like Wise or Remitly?
Yes, in practice. US$10,000 is a useful reference point, not a limit shared by every app. Wise uses it for certain transfers to business accounts; other account combinations and providers have different limits. Confirm the current limit and required documents for your actual payment.
Can’t I just open a bank account in Brazil in my name and then wire transfer funds from my account in the US or Europe to my account in Brazil?
By opening a bank account in Brazil you may be able to transfer your funds from abroad to your bank account in Brazil. You are still required to present documents requested to release the money in Brazil. Additionally, while some banks in Brazil allow bank accounts to be opened remotely, ask whether this is available to you as a nonresident. The proper account for someone living abroad is a nonresident account—see Section 5 of this guide. Confirm that it can receive your proposed transfer.
So with the “CRNM card” am I able to open a bank account? What about the “CPF”?
The CPF is your Brazilian tax identification number. The CRNM is a residence identity card for registered foreign residents. A CPF alone does not guarantee that a bank will open an account, and nonresidents should ask about nonresident accounts. You do not need to become a citizen first.
Taxes and costs
Do I pay tax when sending money to Brazil?
Three different things get confused here. (1) IOF: the Brazilian tax on the currency conversion — see our section above; it is charged on the Brazilian side of the exchange. (2) Income tax: sending money is not by itself a taxable event, but the underlying income, gift, or other transaction may create tax or reporting duties, and unexplained inflows invite scrutiny. (3) Gift tax (ITCMD): if the transfer is a donation — which can include family help with a property purchase — state gift tax may apply. When in doubt, ask before the money moves.
What is IOF and who pays it?
IOF is a federal tax charged on financial operations, including the foreign-exchange contract that converts your currency into reais. It is assessed in Brazil, on the conversion. Ask which rate applies and whether it is embedded in the final quote you receive. The account owners alone do not determine the rate; the payment’s direction and purpose matter too.
Why is my exchange rate worse than the one on Google?
Because of the spread — the markup between the mid-market rate and the rate you are given. It is how most providers actually make their money, and it varies far more than wire fees do. See the total-cost section above.
What is the cheapest way to send money to Brazil?
We advise you not to have cost as the main driver of your decision on how to transfer money to Brazil. All the banks involved in transferring money to Brazil must follow rules for checking and documenting the transfers. These procedures cost money and such cost is naturally factored into the conversion exchange to be applied to your transaction. An attractive rate alone does not prove a provider is unsafe, but verify the provider and question offers that depend on hiding the real parties or purpose.
Property purchases
My parents are helping pay for the property — does that change anything?
Yes. The family contribution must be documented and explained up front. Decide whether it is a gift, a loan, or money from someone who will also own the property. Donations from abroad may trigger state gift tax (ITCMD), but not every family payment is a donation. See our donations page and get advice before the money moves.
What is the best way to go about getting a loan to buy property in Brazil?
Loans in Brazil are more difficult to obtain than in countries such as the US. Lenders may require a Brazilian credit history, suitable residence status, and income they can verify. Acceptance of foreign income varies by lender. A US lender would rarely accept collateral in Brazil. However, if you are able to secure a loan in the US based on other collateral (e.g., a home you own in the US), ask the receiving provider what evidence it needs before using the funds to purchase real estate in Brazil. For off-plan (na planta) purchases, developer financing is sometimes available — see our off-plan guide.
What are the documents usually requested by banks to release a wire transfer sent to Brazil?
A sample list of documents, which may vary depending on the bank: 1. Signed contracts showing the purpose of the payment; 2. Proof of downpayment; 3. Tax returns for the transferor (to show the source of funds) and the recipient if relevant; 4. Copies of bank statements and paystubs to document sources of income; 5. Other documents such as IDs, tax identification numbers, and proof of address for all parties.
What happens if my transfer is returned?
If the recipient bank is not satisfied, it may return the wire to the originating bank — usually after days or weeks, at the exchange rate and fees of the return leg. For property buyers this can create a serious problem: contract deadlines keep running while the money bounces. It is the main reason we insist on the 60–90 day window and on preparing the documents before sending.
Risks, scams, and the law
An individual in Brazil offered to “exchange currencies with me.” Is this a good idea?
Do not use an informal stranger-to-stranger exchange to fund a property purchase. You risk losing all your money if the individual has no intention of giving you reais after receiving your dollars. Not every private currency exchange is automatically a crime, but your purchase funds should use an appropriate regulated route with clear records.
What is the so-called “Dólar-cabo”?
It is an informal arrangement of trading dollars in the gray market for deposit in an institution abroad. This may or may not involve actual cross-border transfers of money. Unauthorized arrangements can lead to criminal consequences, depending on the facts. It is often used in money laundering schemes.
Can I send my payment in tranches to Brazil to make the transfer easier?
Agreed instalments are different from splitting a payment to avoid checks. Tell the provider the full transaction amount and reason for each instalment. Sending money in smaller pieces to hide the real amount or avoid required checks can create serious legal problems. A related term is smurfing. Smurfing is a money-laundering technique involving the structuring of large amounts of cash into multiple small transactions. Smurfs often spread these small transactions over many different accounts, to keep them under regulatory reporting limits and avoid detection.
How to send money anonymously?
We do not recommend any unofficial ways to send money to Brazil either through your name or anonymously. When sending money to Brazil, your number one concern should be safety and certainty that your money will arrive at the right beneficiary. Concerns about getting the best currency rate for the US dollar or other currencies should be secondary.
What are the US laws on sending money abroad?
This guide addresses the Brazilian side of the transfer. You should also check the rules in the United States or your home country. For this purpose, we recommend that you consult with a licensed attorney in your jurisdiction to check on the laws on sending money abroad.
How do I send money FROM Brazil abroad?
Outbound transfers have their own rules: the provider will check the funds’ origin, and tax treatment depends on the transaction. Do not assume an inbound transfer quote applies in the other direction. If the money comes from an inheritance or a property sale, start with our guide on transferring inherited funds from Brazil — or contact us about repatriation.
10. Related videos: buying real estate in Brazil
Watch our Oliveira Lawyers playlist for practical guidance on buying real estate in Brazil, including legal steps, money transfer issues, due diligence, and foreign-buyer risks.
Open the Buying Real Estate Properties in Brazil playlist on YouTube.
Related steps in the buying guide
To learn more about purchasing real estate in Brazil, check our How to Buy Properties in Brazil guide. You can also learn about the advantages of buying real estate in Brazil in our Why Buying Real Estate in Brazil guide. Find opportunities and decide where to buy using our Know Where to Buy Real Estate in Brazil guide. Getting your CPF? Granting a power of attorney for the closing? See our CPF and POA guides.
Before you act
This guide reflects our team’s experience helping foreign clients move funds into Brazil, but it is general information only — it is not legal advice and does not create an attorney-client relationship. Sending money across borders touches banking regulation, tax law, currency controls, and anti-money-laundering rules in at least two countries, and mistakes can result in blocked or returned funds, contractual penalties, tax assessments, and in some cases criminal consequences.
Providers, limits, rates, and regulations mentioned here change frequently and may be outdated by the time you read this. Before sending significant amounts abroad, secure proper legal representation in the relevant jurisdictions.
Legal framework and supporting sources
Checked October 15–16, 2026. Law 14,286/2021 — foreign-exchange framework; Civil Code — ownership registration, article 1,245; Central Bank: receiving money from abroad; Central Bank: transfer limits; Central Bank: nonresident accounts; BCB Resolution 277; BCB Resolution 561: October 2026 changes; Wise: current BRL transfer limits; Wise: BRL payment purposes; IOF decree, consolidated text; Receita Federal: bringing cash to Brazil.